How Corporation Tax marginal relief tapers the rate between 19% and 25%, with a worked example.
The two headline rates
Companies with profits up to £50,000 pay the small profits rate of 19%. Companies with profits over £250,000 pay the main rate of 25%.
The gap in between
Between £50,000 and £250,000, marginal relief tapers the effective rate smoothly between 19% and 25%, rather than jumping straight from one rate to the other — preventing a company just over £50,000 profit from suddenly facing a much higher overall tax bill.
Why it matters for planning
Understanding where your company sits within this taper genuinely affects decisions like the timing of expenditure or dividend planning — worth calculating properly rather than assuming a flat rate applies.
Work out your effective rate with the Payslp Corporation Tax calculator.
Seeing the taper visually
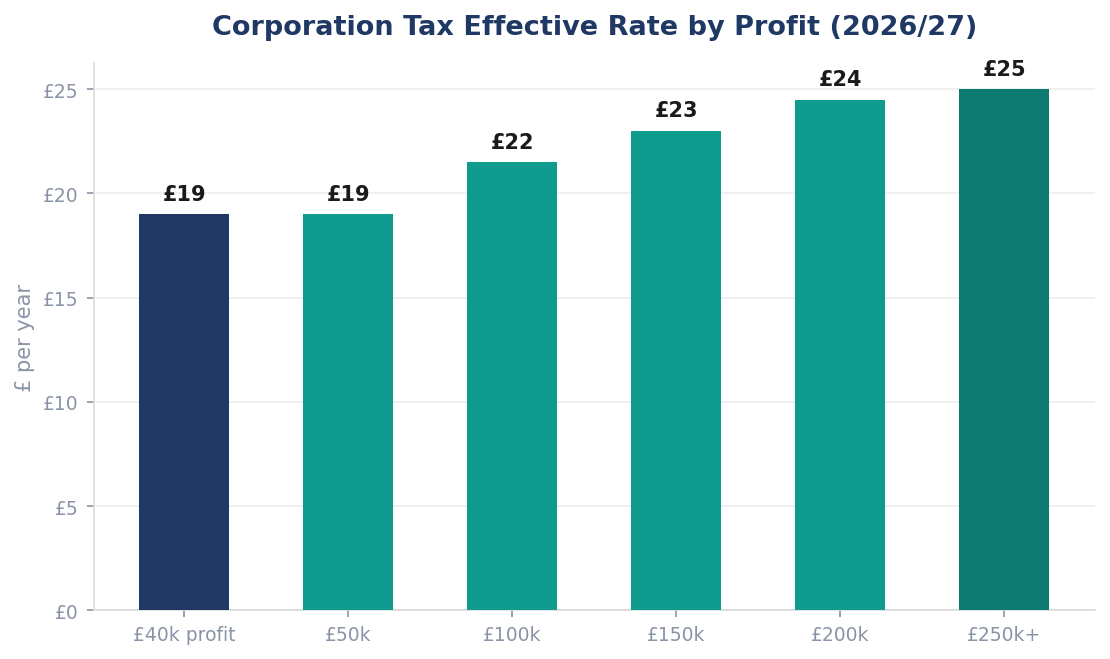
The smooth curve between £50,000 and £250,000 profit is deliberate — it prevents a company from facing a sudden jump in tax rate purely for crossing the small profits threshold by a small margin.
Frequently asked questions
Does marginal relief require a separate claim?
No — it’s calculated automatically as part of your Corporation Tax return, based on your actual profit for the period.